What is the scope and industry significance of the Golf Tourism Market?
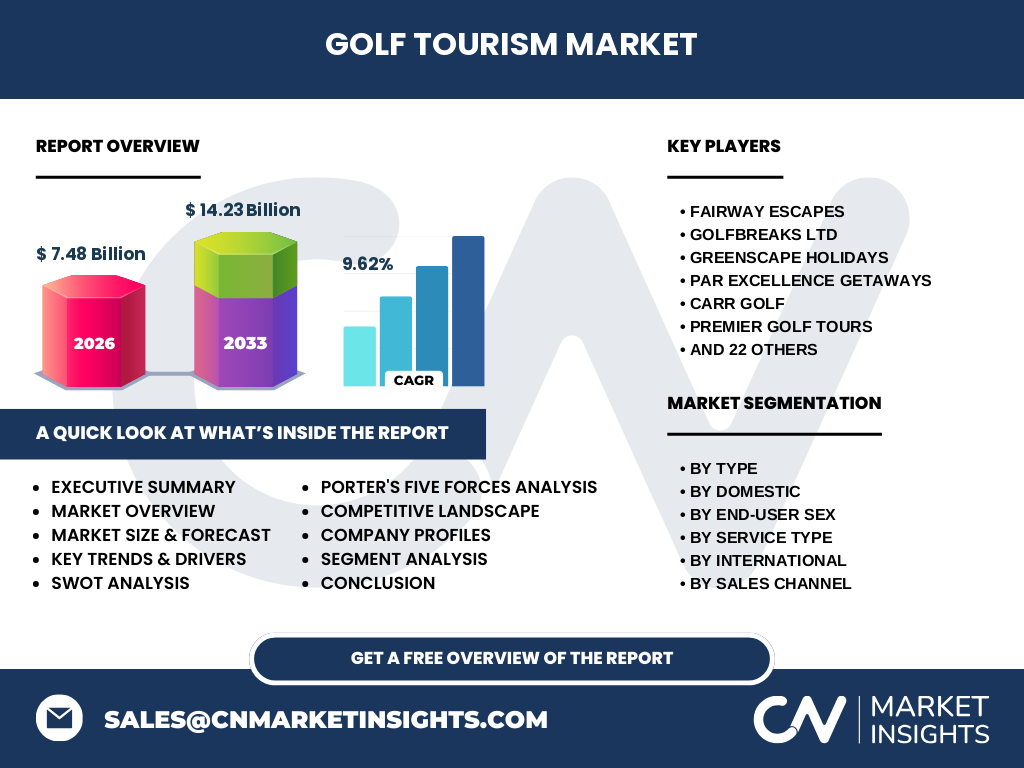
Our analysis indicates that the Golf Tourism Market is valued at 7.48 Billion in 2026, serving as a vital nexus between hospitality, specialized sports logistics, and premium leisure travel. This sector encompasses complex logistical frameworks, including international green-fee bookings, bespoke equipment transit through aviation hubs, and regulatory compliance with bodies such as the R&A and USGA.
Key market drivers, restraints, challenges, and opportunities shaping Golf Tourism Market
Growth is heavily propelled by rising disposable incomes and dedicated enthusiast demographics. However, stringent environmental water regulations and carbon-offset pressures on long-haul flights present severe operational restraints. The primary opportunity lies in integrating luxury wellness packages with premier coastal links, alleviating seasonal capacity bottlenecks.
Emerging trends and growth patterns in Golf Tourism Market
The shift toward experiential travel has elevated demand for culturally immersive itineraries. Industry trends highlight a surge in personalized luxury bookings via digital-first operators like Golfbreaks Ltd and Golfasian Co. Ltd, moving away from rigid, standardized group packages toward hyper-customized multi-destination excursions.
How did the pandemic affect the Golf Tourism Market and what is the recovery trajectory?
The COVID-19 pandemic severely disrupted international mobility, causing unprecedented cancellations across major tournament circuits. The subsequent recovery trajectory has outpaced broader travel sectors, driven by pent-up demand for open-air, socially distanced sporting environments and supported by aggressive stimulus and flexible booking policies from operators.
Competitive benchmarking and strategic dynamics in the Golf Tourism Market
Market concentration remains moderately fragmented, featuring specialized regional experts alongside diversified global giants. Strategic positioning relies on exclusive tee-time allocations at championship courses. Industry leaders like Carr Golf and Celtic Golf leverage deep local relationships to secure high-demand slots that generic aggregators cannot access.
Executive summary of key findings about the Golf Tourism Market
The data suggests a robust expansion for the Golf Tourism Market, projecting a robust CAGR of 9.62% to reach 14.23 Billion by 2033. Success in this landscape increasingly demands digital transformation, sustainability compliance, and strategic partnerships with premier resort destinations worldwide.
Market forecast and revenue trajectory from 2027 to 2033
Driven by compounding consumer interest and expanding middle-class demographics in emerging Asian economies, the market will scale from its 2026 baseline to 14.23 Billion by 2033. This trajectory reflects a sustained 9.62% CAGR, outperforming traditional leisure travel benchmarks.
Segmentation analysis of the Golf Tourism Market
Market architecture divides by Type (Domestic and International), End-User Sex (Male and Female), Service Type (Personal Tours and Professional Tours), Sales Channel (Direct Channel and Distribution Channel), and specific sub-segments like Destination Golf Packages and Regional Travel, each dictating distinct logistical and marketing strategies.
Regional market analysis and geographic distribution
Geographic performance is heavily anchored by historical golf strongholds in Western Europe and North America, while the Asia-Pacific region exhibits the fastest incremental growth. Localized constraints, such as strict land-use zoning in coastal areas, directly dictate regional course availability and subsequent tourism volume.
In-depth regional review of high-performing tourism corridors
Western Europe retains dominance due to legendary links courses in Scotland and Ireland, supported by specialized firms like Scottish Golf Holidays Inc. Concurrently, Southeast Asia is emerging as a premier value-driven hub, capitalizing on modern infrastructure and favorable currency exchanges for international travelers.
Company profiles and strategic positioning of leading market participants
Prominent entities such as Fairway Escapes, Kalos Golf, and Premier Golf Tours differentiate themselves through ultra-personalized service tiers, luxury yacht-golf integrations, and exclusive corporate hospitality packages, capturing high-yield travelers seeking seamless, concierge-level execution.
Porter's Five Forces analysis of competitive intensity
Competitive rivalry is intense among boutique operators, while supplier power is notably high for top-tier championship courses capable of dictating premium green fees. Buyer power remains moderate-to-high due to abundant online comparison platforms, forcing operators to innovate continuously on value-added services.
SWOT analysis of the Golf Tourism Market industry ecosystem
Key strengths include high-spending consumer demographics and unmatched brand equity of historic courses. Weaknesses involve high weather dependency and complex travel logistics. Opportunities emerge in digital booking automation, while threats encompass severe climate change impacts on turf maintenance and geopolitical travel restrictions.
Value chain analysis from raw materials to end-users
The value chain initiates with turf maintenance inputs and course architecture, flowing through hospitality providers, specialized logistics handlers, and tour operators like The Haversham and Baker Co, ultimately delivering packaged experiences to end-user golfers via direct and indirect distribution channels.
Investment insights and high-potential areas for capital deployment
High-potential investment corridors center on tech-enabled booking platforms, eco-sustainable resort upgrades, and emerging secondary golf destinations in Eastern Europe and Latin America. Capital allocators should prioritize firms demonstrating robust ESG compliance and agile supply-chain partnerships.
Conclusion and strategic takeaways for industry stakeholders
The Golf Tourism Market presents exceptional growth opportunities for stakeholders willing to invest in digital modernization and sustainable tourism practices. Navigating regulatory hurdles and meeting evolving consumer expectations for bespoke experiences will separate market leaders from legacy laggards.
Research methodology and data triangulation framework
Baseline estimates are meticulously triangulated by synthesizing cross-border trade registry data, primary executive interviews with operators such as GolfHolidays.com and Direct Golf Holidays, and secondary macroeconomic indicators regarding discretionary travel spend and global tourism metrics.
Scope of the report, coverage parameters, and operational limitations
This report covers global consumption of golf-related travel services through 2033, analyzing quantitative revenues and qualitative market shifts. Limitations include potential unforeseen macroeconomic shocks, regulatory policy shifts regarding carbon emissions, and localized weather anomalies affecting seasonal play.
Recent developments, strategic partnerships, and corporate maneuvers
Recent market dynamics feature aggressive digital expansion, with firms like Ascot Golf Tours and TeeTime Travels forging strategic alliances with major airline carriers and luxury hotel chains to offer seamless, all-inclusive travel packages designed to capture post-pandemic luxury spend.